The Dilution Ledger: How New Shares Quietly Reshape Your Slice of a Company
A shareholder can own exactly the same number of shares for years and still end up owning a smaller percentage of the company. Nothing disappeared from the brokerage account. The denominator changed. New shares were issued, awards vested, options were exercised, or securities became common stock. That quiet change is dilution.
Dilution is often discussed as if it were a single percentage hidden in one line of a filing. In practice, several share counts answer different questions, and potential shares do not all become real on the same date or under the same conditions. A dilution ledger is a repeatable way to track the moving denominator, connect it to the reason shares changed, and judge whether the company created enough value to justify the smaller ownership slice. It is an educational tool, not a forecast or a recommendation to buy, hold, or sell any security.
Begin With the Ownership Fraction
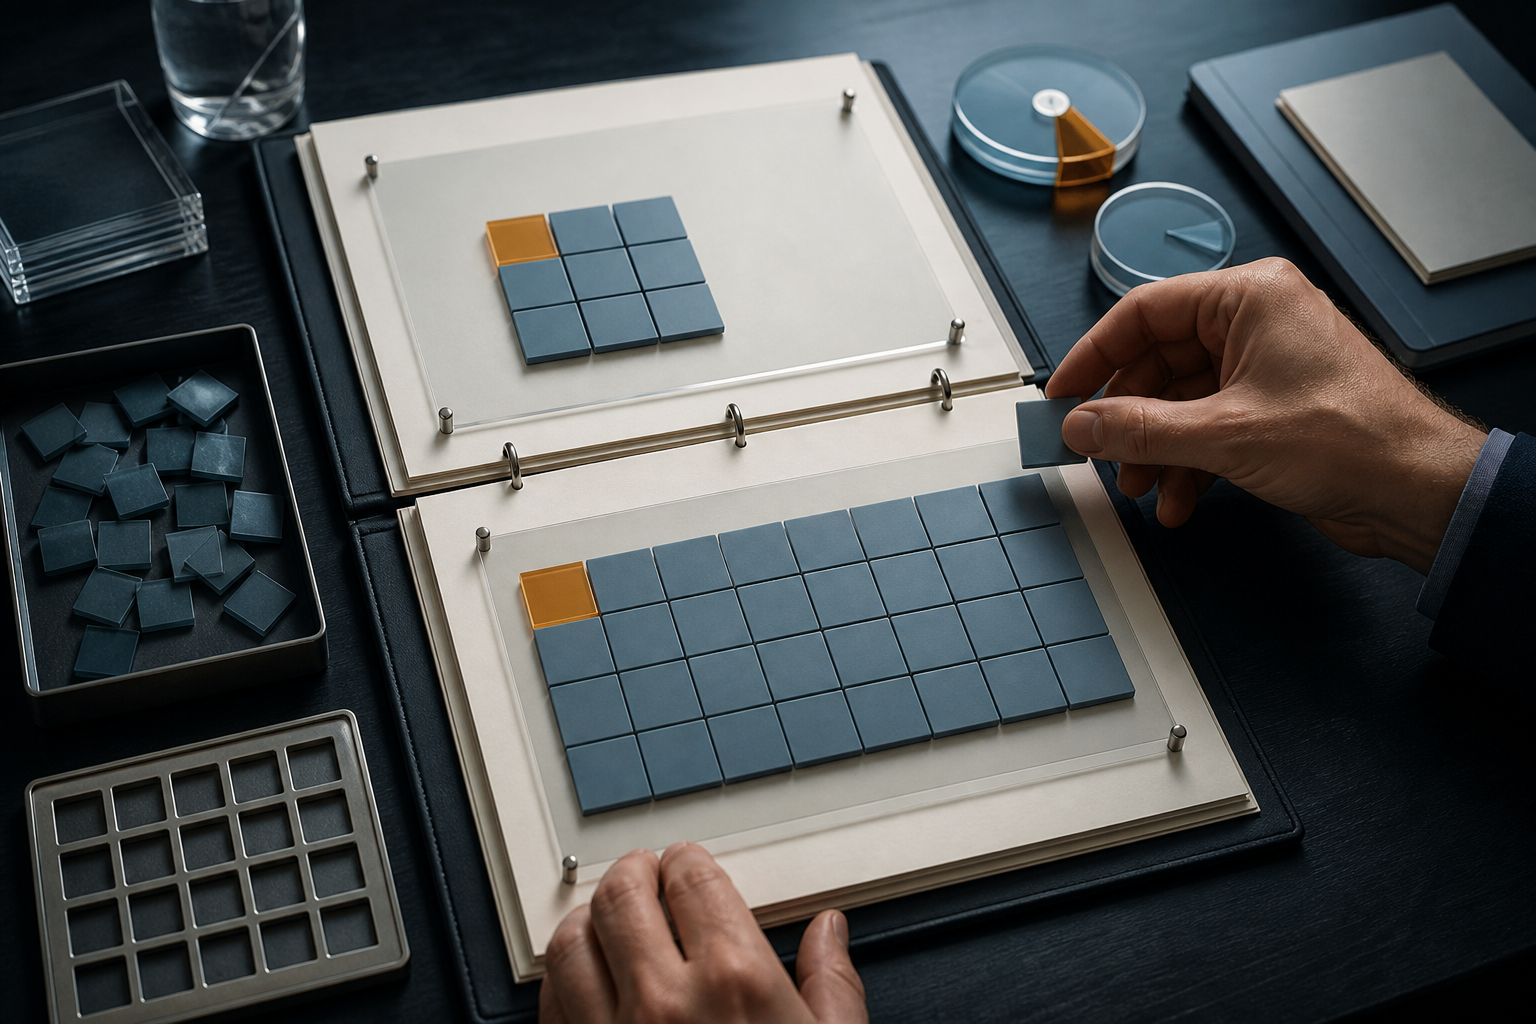
Ownership percentage is shares owned divided by total shares outstanding. If an investor owns 100 shares when a company has 10,000 outstanding, the fraction is one percent. If the company issues 2,500 new shares and the investor still owns 100, the fraction falls to 0.8 percent. The investor has not lost shares; the company has expanded the ownership base.
This arithmetic is simple, but its economic meaning depends on what the company received. Issuing shares for cash, an acquired business, employee service, or debt conversion can alter assets, liabilities, talent, earning capacity, and risk. A smaller fraction of a stronger company can be worth more than a larger fraction of a weaker one. Dilution describes the change in the slice, not the quality of the exchange.
The ledger therefore records both sides: how many shares or potential shares appeared, and what value or obligation was associated with them. It resists two shortcuts—treating every issuance as automatically destructive and treating growth in the total company as proof that per-share owners benefited.
Separate the Share Counts Before Comparing Them
“Shares” can refer to authorized shares, issued shares, outstanding shares, a period’s weighted-average shares, or a diluted weighted average used for earnings per share. These are not interchangeable. Authorized shares set a legal ceiling under governing documents. Issued shares have been created. Outstanding shares generally exclude shares the company holds in treasury. Weighted averages reflect how long shares were outstanding during a reporting period.
The basic earnings-per-share denominator is usually a weighted-average count, not simply the number outstanding on the final day. The diluted denominator can add the effect of instruments that may produce common shares, subject to accounting rules and anti-dilution tests. It is designed for a period’s earnings-per-share calculation; it is not a universal forecast of the future cap table.
Label every number in the ledger with its definition, date or period, and document location. Comparing a quarter-end outstanding count with last year’s diluted weighted average can manufacture a trend that does not exist. Consistent columns matter more than false precision.
Establish a Clean Opening Balance
Start with the common shares outstanding at the end of the prior comparable period. Record each class separately if voting or conversion rights differ, then add a clearly explained common-equivalent view only when it is useful. Preserve the source date because an annual report, quarterly report, proxy statement, and later event filing may describe different moments.
Next, reconcile toward the current period. Common movements include public or private offerings, shares issued in acquisitions, employee-plan issuance, option exercises, restricted awards that vest, conversions, employee purchase plans, dividend reinvestment, repurchases, and retirements. Some filings provide a roll-forward; elsewhere the reader must assemble the movement from equity notes, cash-flow disclosures, compensation notes, acquisition terms, and subsequent events.
Use a difference column as a control. Current outstanding shares minus opening outstanding shares should equal net documented additions and reductions, subject to timing, rounding, and class changes. An unexplained remainder is a question, not a number to force into a convenient category.
Record Primary Issuance as an Exchange
When a company sells newly issued shares, the denominator increases and the company receives capital after offering costs. Record the number of shares, issue price if disclosed, gross proceeds, net proceeds, stated use, and timing. Then distinguish the financing event from management’s later deployment of the cash.
An issuance can extend a cash runway, reduce debt, fund capacity, or support an acquisition. Those outcomes may improve the enterprise, but they are not guaranteed merely because capital was raised. The ledger should avoid crediting projected benefits before evidence appears. Track the promised use separately from actual cash deployment and operating results.
Watch for at-the-market programs and shelf registrations. Authorization to sell securities is not the same as completed issuance, and a maximum program size is not the number of shares actually sold. Use completed-period disclosure for the realized ledger and keep unused capacity in a clearly labeled potential column.
Translate Equity Compensation Into Share Movement
Stock options, restricted stock units, performance awards, and employee purchase plans can connect compensation to equity. Their effects arrive through different paths. An option may never be exercised, may expire, or may create fewer incremental shares in a diluted earnings calculation than its gross underlying amount. A restricted unit may be forfeited, vest into shares, or have some shares withheld for taxes.
Maintain three views: awards granted during the period, awards outstanding at period end, and shares actually issued or released. Grants show the new commitment, the outstanding table shows overhang and conditions, and issuance affects the legal outstanding count. Do not simply add every award balance to current common shares; that can double count vested awards already included or ignore cancellations.
Also record stock-based compensation expense, but do not confuse expense with share issuance. Expense recognizes compensation under accounting rules over service or performance periods. The cash-flow statement may add a noncash portion back within operating cash flow, yet the awards can still transfer part of future ownership. Cash economics, reported expense, and dilution are related but distinct.
Handle Options With More Than One Lens
The gross option count is useful for understanding contractual exposure, but diluted earnings per share commonly uses a treasury-stock-style method for dilutive options and similar instruments. In simplified terms, the calculation assumes exercise and then assumes proceeds are used to repurchase shares at an average market price. The incremental amount can therefore be smaller than the gross option total.
That accounting result changes with exercise prices, market prices, unrecognized compensation, tax effects, and anti-dilutive treatment. Options excluded from diluted earnings per share in a loss period do not vanish. They may remain outstanding and could become dilutive in another period. The ledger should record both reported diluted incremental shares and gross instruments outstanding, with an explanation of why they differ.
Avoid inventing a single “fully diluted” total without defining assumptions. A cap-table view that counts every option may answer a different question from a reported earnings-per-share denominator. Both can be useful when labeled; neither should silently replace the other.
Track Restricted and Performance Awards Carefully
Restricted stock and restricted units are often easier to overlook because they may not require an exercise payment. Time-based awards generally depend on continued service, while performance awards can depend on operational, financial, or market conditions and may settle across a range. The maximum award opportunity can be substantially larger than the amount ultimately earned.
Record unvested balances, new grants, vesting or release, forfeitures, and the range attached to performance awards. Note whether the disclosed number represents target or maximum units. If shares are withheld for taxes at settlement, distinguish gross units vested from net shares delivered; the company may use cash or remit value associated with the withheld portion.
Read the compensation discussion alongside the financial-statement note. The first explains design and incentives; the second often provides award movement and expense. Together they help the ledger show whether recurring grants are offsetting forfeitures and repurchases or steadily expanding the ownership claim.
Unpack Convertibles, Warrants, and Contingent Shares
Convertible debt or preferred stock can create common shares when holders exercise conversion rights or when specified conditions are met. Warrants provide purchase rights under stated terms. Acquisition agreements may promise additional shares if milestones occur. These instruments require a condition column: conversion price or ratio, maturity, triggers, adjustment provisions, and the maximum or expected shares described in the filing.
Potential dilution can change when terms reset. Some instruments protect holders from later low-priced issuance by adjusting conversion or exercise terms. Variable-price conversions can produce more shares when the market price falls. Readers should rely on the actual agreement and risk disclosures because instrument names alone do not describe the share outcome.
For the realized ledger, record shares only when issued into the outstanding count. For the potential ledger, show scenarios without pretending that all conditions will occur simultaneously. State assumptions next to every scenario and avoid adding mutually exclusive outcomes.
Analyze Acquisitions on a Per-Share Basis
A share-funded acquisition increases the denominator in exchange for another business or asset. The headline purchase price does not establish whether existing holders benefited. Record shares issued at closing, contingent equity, assumed awards, and any later earn-out shares. Then follow revenue, profit, cash flow, integration costs, debt, and impairment evidence over time.
Management may describe an acquisition as accretive, meaning it is expected to increase a chosen per-share measure. That claim depends on forecasts, timing, financing, accounting adjustments, and the metric selected. Preserve the claim as a claim, then compare later outcomes using consistent measures.
The ledger asks a disciplined question: did the acquired earning power or strategic capacity grow faster than the claim count, after considering risk and resources consumed? The answer may remain uncertain for years. Tracking the original exchange prevents the new shares from disappearing into a much larger financial statement.
Keep Repurchases in the Same Ledger
Repurchases can reduce outstanding shares, but an announced authorization is only permission. Record shares actually repurchased, average price, cash spent, whether shares were retired or held in treasury, and period-end outstanding shares. Compare the reduction with concurrent employee issuance and acquisition shares.
A company can spend heavily on repurchases while the share count barely changes because compensation issuance offsets the purchases. That does not make compensation or repurchases inherently wrong; it changes the description. Part of the cash may be preventing dilution rather than shrinking the ownership base.
Evaluate the balance-sheet context. Cash used for repurchases cannot simultaneously fund operations, investment, or debt reduction. The dilution ledger supplies the denominator evidence, while a broader capital-allocation analysis considers price paid, financial resilience, and alternative uses. Combining the two avoids celebrating a lower share count without examining its cost.
Compare Per-Share Outcomes, Not Just Company Totals
Revenue, earnings, free cash flow, and book value can grow while the outcome per share grows more slowly or declines. Place selected company totals beside consistent basic and diluted per-share measures. If revenue rises ten percent while the relevant share count rises eight percent, revenue per share increases by much less than the headline growth rate.
Use caution with losses. Diluted earnings per share may exclude potential shares when including them would make the reported loss per share look smaller, because that result would be anti-dilutive. A basic and diluted denominator that appear equal during a loss period does not prove that no options, awards, or convertibles exist. Check the note for excluded instruments.
No per-share measure is sufficient alone. Earnings can be affected by estimates and one-time items; cash flow can swing with working capital; book value may poorly represent some businesses. The ledger is strongest when it makes denominator changes visible across several relevant numerators.
Run the Ledger as a Quarterly Reconciliation
Create columns for the date, instrument or transaction, gross potential shares, shares actually issued, shares repurchased or retired, ending outstanding shares, diluted weighted-average effect, consideration received or cash spent, vesting or conversion conditions, and document note. Add a short management explanation and a separate analyst question.
Each quarter, begin with the prior ending balance and reconcile the new ending balance. Update potential instruments even if they created no shares. Compare year-over-year weighted averages as well as point-in-time counts. Mark subsequent events that occurred after the balance-sheet date so they do not leak backward into the period.
Finish with four questions. What caused the denominator to move? What did the company receive or avoid paying? Which potential claims could matter next? Did the relevant per-share outcomes improve after the exchange? The questions make the ledger useful without converting it into a mechanical score.
Read the Denominator With Humility
Dilution analysis is precise about arithmetic but uncertain about value. New capital can rescue a constrained company or finance an unproductive expansion. Equity awards can support retention or become an expensive recurring transfer. Convertibles can lower near-term cash interest while creating a large contingent claim. Repurchases can be disciplined or poorly timed.
The ledger cannot settle those judgments on its own. It can prevent the ownership denominator from being ignored and keep unlike share counts from being compared. It also creates a record of what management said the issuance would accomplish, making later evaluation less vulnerable to hindsight.
For an investor, the practical habit is simple: count the slices, identify how they were created, record what came back to the company, and examine results per slice over time. Anyone making a personal investment decision should consider their own objectives, risk capacity, taxes, time horizon, and the value of advice from an appropriately qualified professional. The ledger is a reading framework, not individualized financial advice.